What the straddle price is
A straddle combines a call and a put on the same underlying, strike and expiry. The chart often starts with the at-the-money strike, but a straddle can use another strike. The straddle price is the sum of the two last traded prices. If the Nifty 24,500 call trades at 110 and the 24,500 put at 95, the straddle price is 205 points.
Two numbers fall out of that price immediately. The breakevens of a long straddle sit at the strike plus and minus the combined premium (24,295 and 24,705 in the example). And the premium itself is the market's price for movement: a larger straddle means options are pricing a bigger swing, or more time, or both.
| Driver | Effect on straddle price | Where you see it |
|---|---|---|
| Time to expiry | Shrinks as expiry nears; the fall accelerates in the last sessions | Gradual downward slope through the day and week |
| Implied volatility | Higher IV lifts both legs; lower IV deflates both | Spikes around events, deflation after them |
| Spot movement | Moves the strike away from the money; a rolling chart re-centres, a fixed strike does not | Jumps when the ATM strike changes |
Straddle price and the expected move
For an at-the-money option the Black-Scholes price is close to 0.4 × spot × volatility × the square root of time, so the call plus put is close to 0.8 × spot × volatility × the square root of time. That is roughly the market-implied expected absolute move to expiry, and about 80% of a one-standard-deviation move.
In practice this means the straddle price is a quick read on how many points the market is pricing between now and expiry. Compare it with how far the index has actually moved in comparable sessions. A straddle that is consistently larger than realised movement shows options being priced rich; the reverse shows them cheap.
The straddle price is an approximation built on the ATM strike. It ignores skew, rate and dividend effects, and last traded prices can differ from the quotes you could actually trade at.
How to read a straddle chart
- Confirm the contract. Check the symbol, expiry and whether the chart uses a fixed strike or a rolling ATM strike. A strike change on a rolling chart creates a step that is not a real repricing.
- Read the slope. In a quiet session the line should drift down as time decay works. A flat or rising line means volatility or movement is offsetting decay.
- Look at VWAP. The session volume-weighted average of the premium is a reference. Premium that stays below VWAP is decaying through the day; premium that holds above it is being bid.
- Check the synthetic future. Strike plus call minus put is the futures-equivalent price implied by the two options. A persistent gap to the futures price points at carry or positioning rather than direction.
- Compare with other sessions. Use the historical mode to overlay the same time of day and the same distance to expiry, so you are comparing like for like.
Expiry-day behaviour
In the last hours before expiry time value falls quickly while gamma at the money is at its highest, so a small move in spot changes both legs sharply. The straddle price becomes very sensitive to where spot sits relative to the strike. This is why intraday charts on expiry day often show steep falls interrupted by sharp spikes when spot moves toward a strike.
Because the contract is closest to expiry, the premium is smallest in absolute terms, so a few rupees of bid-ask spread matter more. Treat the tick-by-tick shape as noisy and focus on the broader slope.
Use the straddle chart and check the legs
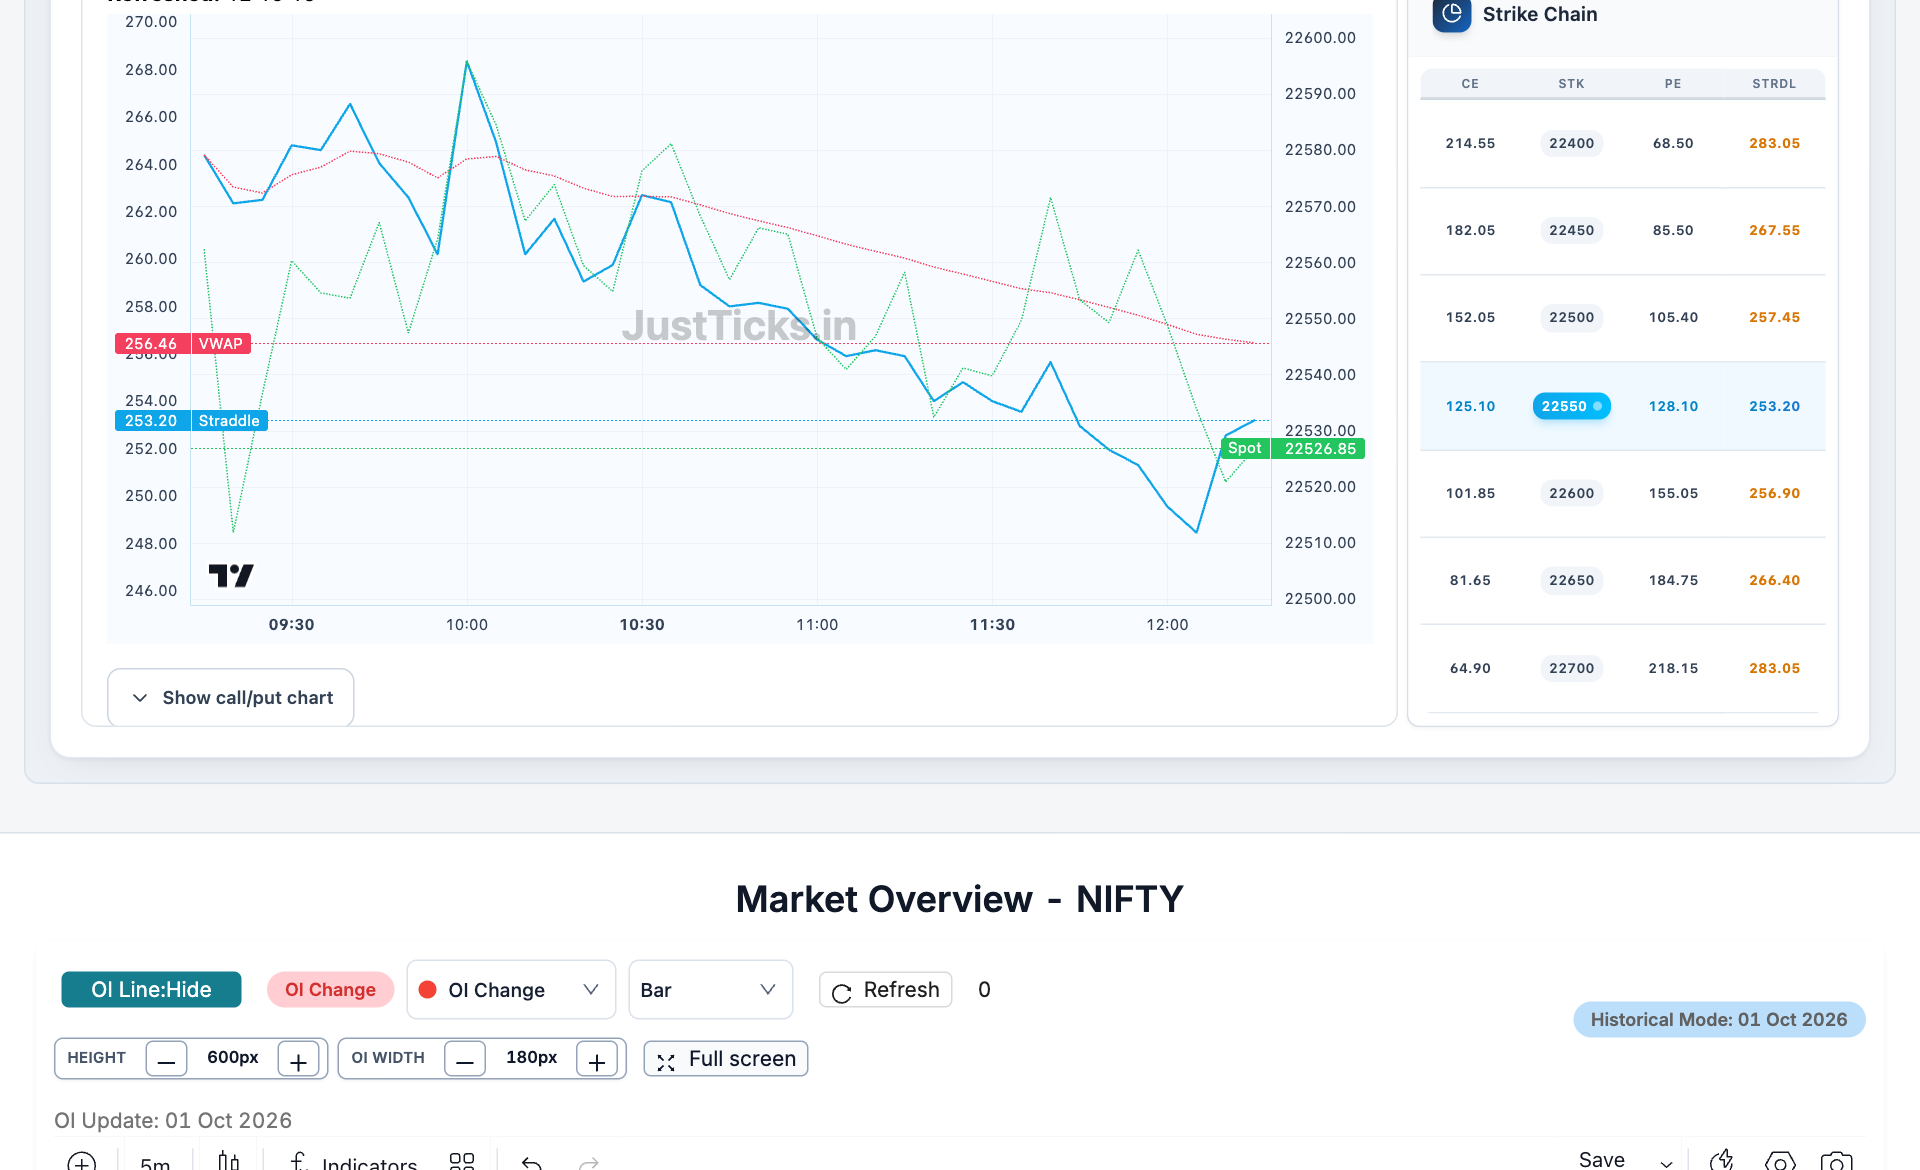
- Check both legs. The selected strike row shows CE 125.10 plus PE 128.10, which equals 253.20 points.
- Combined premium. This is the observed call-plus-put price, not profit from a long or short position.
- Session VWAP. VWAP is a same-session reference rather than your own entry price.
- Separate spot axis. Spot uses index points on the right; a line crossing does not make it equal to the premium.
- Open the Straddle Chart, select the underlying and expiry, and confirm the session date.
- Select the strike in the chain. Check CE plus PE against the displayed straddle premium; the same strike and expiry must apply to both legs.
- Compare the premium line with VWAP and the underlying-price axis. These are different measures, so visual line crossings do not establish equality.
- Use a past session to inspect a complete example, matching time to expiry when comparing it with another day.
- For changing ATM strikes use the rolling straddle chart. To model long or short legs, quantities and expiry P&L, use Strategy Builder.
The screenshot's 253.20-point premium is a price observation, not the profit from holding either a long or short position. Entry prices, quantities and the exit or valuation time are needed for P&L.
Limits of the chart
- It is not a signal. A rising or falling straddle describes what options are pricing. It does not say which direction spot will move.
- Last traded price is not a quote. Illiquid strikes can show stale prints; confirm both legs traded recently.
- It is not trade P&L. The line excludes brokerage, taxes and slippage, and a fixed position's result depends on entry price.
- Different underlyings are not comparable by absolute value. Compare the straddle as a percentage of spot, or against the same underlying's history.
Further reading
OCC's Options Industry Council: long straddle structure. A straddle uses the same strike and expiry for both legs; being at the money is a selection choice, not part of the definition.